
Double Entry Bookkeeping Definition
Product Information
Content
When entries are made in the double entry system, there must be a debit entry and a credit entry into the general ledger. A debit records an entry on the left side of an account ledger, while a credit records an entry on the right side of the ledger. The totals for all debit entries made must always match the totals for all credit entries made; when this is the case, an entry is said to be in balance.
The Future of Money: A History – CoinDesk
The Future of Money: A History.
Posted: Mon, 29 Nov 2021 08:00:00 GMT [source]
In accounting, a debit refers to an entry on the left side of an account ledger, and credit refers to an entry on the right side of an account ledger. To be in balance, the total of debits and credits for a transaction must be equal. Debits do not always equate to increases and credits do not always equate to decreases.
How To Use Excel As A General Accounting Ledger
Because the business has accumulated more assets, a debit to the asset account for the cost of the purchase ($250,000) will be made. To account for the credit purchase, a credit entry of $250,000 will be made to notes payable. The debit entry increases the asset balance and the credit entry increases the notes payable liability balance by the same amount. Contra liability accounts and contra expense accounts—like their contra asset counterparts—also reverse the debit/credit «rules» from the table in the previous section.
This is a simple journal entry because the entry posts one debit and one credit entry. The company should debit $5,000 from the Wood-Inventory account and credit $5,000 to the Cash account. Although you can track net income and formulate an income statement using a single-entry system, you won’t be able to put together a balance sheet. A balance sheet provides you with a more accurate depiction of your business because it allows you to see the owner’s equity, which is the total net worth of your firm.
What is the difference between single and double entry accounting?
Recording method: Single-entry bookkeeping gives a one-sided picture of transactions recorded in the cash register. In double entry, changes due to one transaction are reflected in at least two accounts. … Error detection: In double entry, debits and credits must always be the same.
«Accounts payable» refers to an account within the general ledger representing a company’s obligation to pay off a short-term debt to its creditors or suppliers. David Kindness is a Certified Public Accountant and an expert in the fields of financial accounting, corporate and individual tax planning and preparation, and investing and retirement planning. David has helped thousands of clients improve their accounting and financial systems, create budgets, and minimize their taxes.
What Documents Are Used To Record Entries?
All these entries get summarized in a trial balance, which shows the account balances and the totals of your total credits and total debits. If done correctly, your trial balance should show that the credit balance is the same as the debit balance. It is important for us to consider perspective when attempting to understand the concepts of debits and credits.
We’ll do one month of your bookkeeping and prepare a set of financial statements for you to keep. That’s a win because financial statements can help you make better decisions about what to spend money on in the future. When you send an invoice to a client after finishing a project, you would “debit” accounts receivable and “credit” the sales account. Recording transactions this way provides you with a detailed, comprehensive view of your financials—one that you couldn’t get using simpler systems like single-entry. All small businesses with significant assets, liabilities or inventory. In fact, a double-entry bookkeeping system is essential to any company with more than one employee or that has inventory, debts or several accounts.
The double-entry system has two equal and corresponding sides known as debit and credit. A transaction in double-entry bookkeeping always affects at least two accounts, always includes at least one debit and one credit, and always has total debits and total credits that are equal. It’s easier to explain debits and credits as accounting concepts, as opposed to physical things. Every transaction within your business produces a debit in one account and a credit in the other. Together, they represent money flowing into and out of your business — as one account increases, another has to decrease. A transaction that increases your assets, for example, would be recorded as a debit to that particular assets account. On the flip side, that transaction would also get recorded as a credit in another account.
All U.S. public companies must be GAAP compliant for financial reporting purposes. Additionally, most lenders require GAAP-compliant financial statements when evaluating loan applications from any private or public company. In single-entry bookkeeping, you maintain a cash book in which you record your income and expenses. Start with your existing cash balance for a given period, then add the income you receive and subtract your expenses. After you factor in all these transactions, at the end of the given period, you calculate the cash balance you are left with. Single-entry bookkeeping is a simple and straightforward method of bookkeeping in which each transaction is recorded as a single-entry in a journal. This is a cash-based bookkeeping method that tracks incoming and outgoing cash in a journal.
How To Set Up Accounting Systems For Startup Companies
The total debits and credits must balance, meaning they have to account for the total dollar value of a transactions. A transaction for $1000 must be credited $1000 and debited $1000. A general ledger is the record-keeping system for a company’s financial data, with debit and credit account records validated by a trial balance. The advantages of double entry system far outweigh its disadvantages. Double entry system has, therefore, become the standard and in many cases a basic requirement for maintaining accounting records of medium and large size businesses. Most of the manual and computerized accounting systems are based on it. Under this system, a trial balance can be prepared to check arithmetical accuracy of all accounting entries.
Each transaction (let’s say $100) is recorded by a debit entry of $100 in one account, and a credit entry of $100 in another account. When people say that “debits must equal credits” they do not mean that the two columns of any ledger account must be equal. If that were the case, every account would have a zero balance , which is often not the case. The rule that total debits equal the total credits applies when all accounts are totaled.
This may influence which products we review and write about , but it in no way affects our recommendations or advice, which are grounded in thousands of hours of research. Our partners cannot pay us to guarantee favorable reviews of their products or services.
Origins Of Double Entry Bookkeeping
The books – or ledger – for a business are made up of five main accounts, which are split into groups. In addition to the journals, some companies maintain separate books for some of their important accounts for better control. When a business enterprise presents all the relevant financial information in a structured and easy to understand manner, it is called a financial statement. The purpose of financial statements are to provide both business insiders and outsiders a concise, clear picture of the current financial status in the business. Therefore, the people who use the statements must be confident in its accuracy. When an audit is completed, the auditor will issue a report regarding whether the statements are accurate.
The type of account dictates whether it has a normal debit balance or a normal credit balance, and therefore whether debits or credits increase the balance. In the double-entry accounting system, at least two accounting entries are required to record each financial transaction. These entries may occur in asset, liability, equity, expense, or revenue accounts. If the accounting entries are recorded without error, the aggregate balance of all accounts having Debit balances will be equal to the aggregate balance of all accounts having Credit balances. The accounting entries are recorded in the «Books of Accounts». Regardless of which accounts and how many are involved by a given transaction, the fundamental accounting equation of assets equal liabilities plus equity will hold. The fundamental accounting equation can actually be expressed in two different ways.
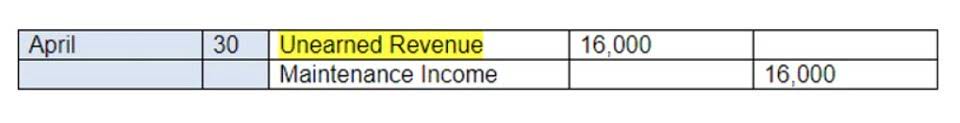
Credits increase revenue, liabilities and equity accounts, whereas debits increase asset and expense accounts. Debits are recorded on the left side of the page and credits are recorded on the right. The sum of every debit and its corresponding credit should always be zero.
A Small Business Owner’s Guide To Double
Exhibit 1 summarizes debit and credit conventions for the five account types. All public companies and almost all large firms nevertheless choose the double-entry approach. They choose double-entry accounting because it is nearly impossible for them to meet government and regulatory requirements for reporting and record-keeping using a single-entry system. And, with a single-entry system alone, large firms cannot accurately track their assets, liabilities, equities, revenues, and expenses.
You will learn how to prepare journal entries in another lesson. For a head start, let us take a look at how we came up with the journal entry for the first transaction. In that transaction, Mr. Briggs invested $30,000 to start a marketing consultation business on October 1, 2020. It’s ours; therefore, from the bank’s perspective the deposit is viewed as a liability .
Balance Sheet Contra Assets Example
Intangible assets are identifiable non-monetary assets that cannot be seen, touched or physically measured, are created through time and effort, and are identifiable as a separate asset. Current assets include inventory, while fixed assets include such items as buildings and equipment. The term accrual is also often used as an abbreviation for the terms accrued expense and accrued revenue. In this example, the company would debit $30,000 for the machine, credit $5,000 in the Cash account, and credit $25,000 in a Bank Loan – Accounts Payable account. The total debit balance of $30,000 matches the total credit balance of $30,000. It means an accurate and consistent double-entry accounting function will lead to a consistent ledger and eventually accurate financial statements of a business. The general ledger of an entity forms the basis of the accounting function.
This transaction results in a decrease in accounts payable and an decrease in cash/ cash or equivalents. When an audit is completed, the auditor will issue a report with the findings.
Is a bookkeeper liable?
Journal entry error: As a bookkeeper you are responsible for recording the day-to-day financial transactions for small businesses which can be an activity prone to simple human error. Professional liability insurance could protect you if you face a claim for negligence, even if you haven’t made a mistake.
Hence, the account Cash will be debited for $10,000 and the liability Loans Payable will be credited for $10,000. Credits to one account must equal debits to another to keep the equation in balance. Accountants use debit and credit entries to record transactions to each account, and each of the accounts in this equation show on a company’s balance sheet. To fully understand debits and credits, you first need to understand the concept of double-entry accounting. Double-entry accounting states that for every financial transaction recorded at least two accounts in your chart of accounts are affected—and they’re affected in equal and opposite ways.
What Is The Double Entry Concept In Accounting?
A double-entry bookkeeping system involves two different “columns;” debits on the left, credits on the right. Every transaction and all financial reports must have the total debits equal to the total credits. A mark in the credit column will increase a company’s liability, income and capital accounts, but decrease its asset and expense accounts. A mark in the debit column will increase a company’s asset and expense accounts, but decrease its liability, income double entry accounting and capital account. The double entry system of accounting or bookkeeping is based on the fact that each business transaction essentially brings two financial changes in business. These changes are recorded as debits or credits in two or more different accounts using certain rules known as ‘rules of debit and credit’. In double entry system, every debit entry must have a corresponding credit entry and every credit entry must have a corresponding debit entry.
The system might sound like double the work, but it paints a more complete picture of how money is moving through your business. And nowadays, accounting software manages a large portion of the process behind the scenes. The Financial Accounting Standards Board governs the generally accepted accounting principles , which are the official rules and methods for double-entry bookkeeping. The idea behind the double entry system is that every business transaction affects multiple parts of the business. For example, when a company receives a loan from a bank, cash is received and an obligation is owed. As a company’s business grows, the likelihood of clerical errors increases. Although double-entry accounting does not prevent errors entirely, it limits the effect any errors have on the overall accounts.
- The first accounts of the double entry bookkeeping system was documented in 1494 by Luca Pacioli, a Franciscan monk and hailed as the Father of Modern Accounting.
- When you generate a balance sheet in double-entry bookkeeping, your liabilities and equity (net worth or “capital”) must equal assets.
- This is a partial check that each and every transaction has been correctly recorded.
- Most computer accounting software uses double-entry techniques, although these generally happen within the software.
- The accounting entries are recorded in the «Books of Accounts».
However, as can be seen from the examples of daybooks shown below, it is still necessary to check, within each daybook, that the postings from the daybook balance. Expense accounts show money spent, including purchased goods for sale, payroll costs, rent, and advertising. Double-entry accounting has been in use for hundreds, if not thousands, of years; it was first documented in a book by Luca Pacioli in Italy in 1494. A bakery purchases a fleet of refrigerated delivery trucks on credit; the total credit purchase was $250,000.
Let’s assume you have a $5000 cash balance at the beginning of the first week in June. The concept of double-entry bookkeeping can date back to the Romans and early Medieval Middle Eastern civilizations, where simplified versions of the method can be found. If you want your business to be taken seriously—by investors, banks, potential buyers—you should be using double-entry. Can provide valuable insight into a company’s financial health.
Want to learn how software can help speed up the process of bookkeeping? AccountsCreditAssets–Expenses–Liability+Equity+Income+Remember when Bob’s Barber Shop sold some hair gel for $45 cash? Well, since we know there is always an equal credit entry to a debit entry, we know we must credit an account in order to balance out the transaction.
